12 Oct 2026
5 key reasons to get your estate in order now

Families often share the same goals, but not always the same definition of a fair outcome.
Ownership decisions should support both family objectives and the long-term viability of the farming business.
Effective succession planning considers leadership capability as well as ownership.
A clear understanding of retirement income needs can help shape better succession decisions.
Illness, death, divorce or changing family circumstances can quickly derail an unprepared plan.
The right ownership and business structures can make succession smoother and more tax effective.
Informal family agreements can create uncertainty if they aren't properly documented.
Considering the interests of all family members early can help reduce future conflict.
Successful transitions rarely happen overnight and often require years of planning and development.
Regularly reviewing wills, powers of attorney and succession documents can provide valuable peace of mind.
Leaving conversations too late
Assuming everyone wants the same outcome
Focusing on tax alone
Not understanding retirement funding needs
Failing to document agreements
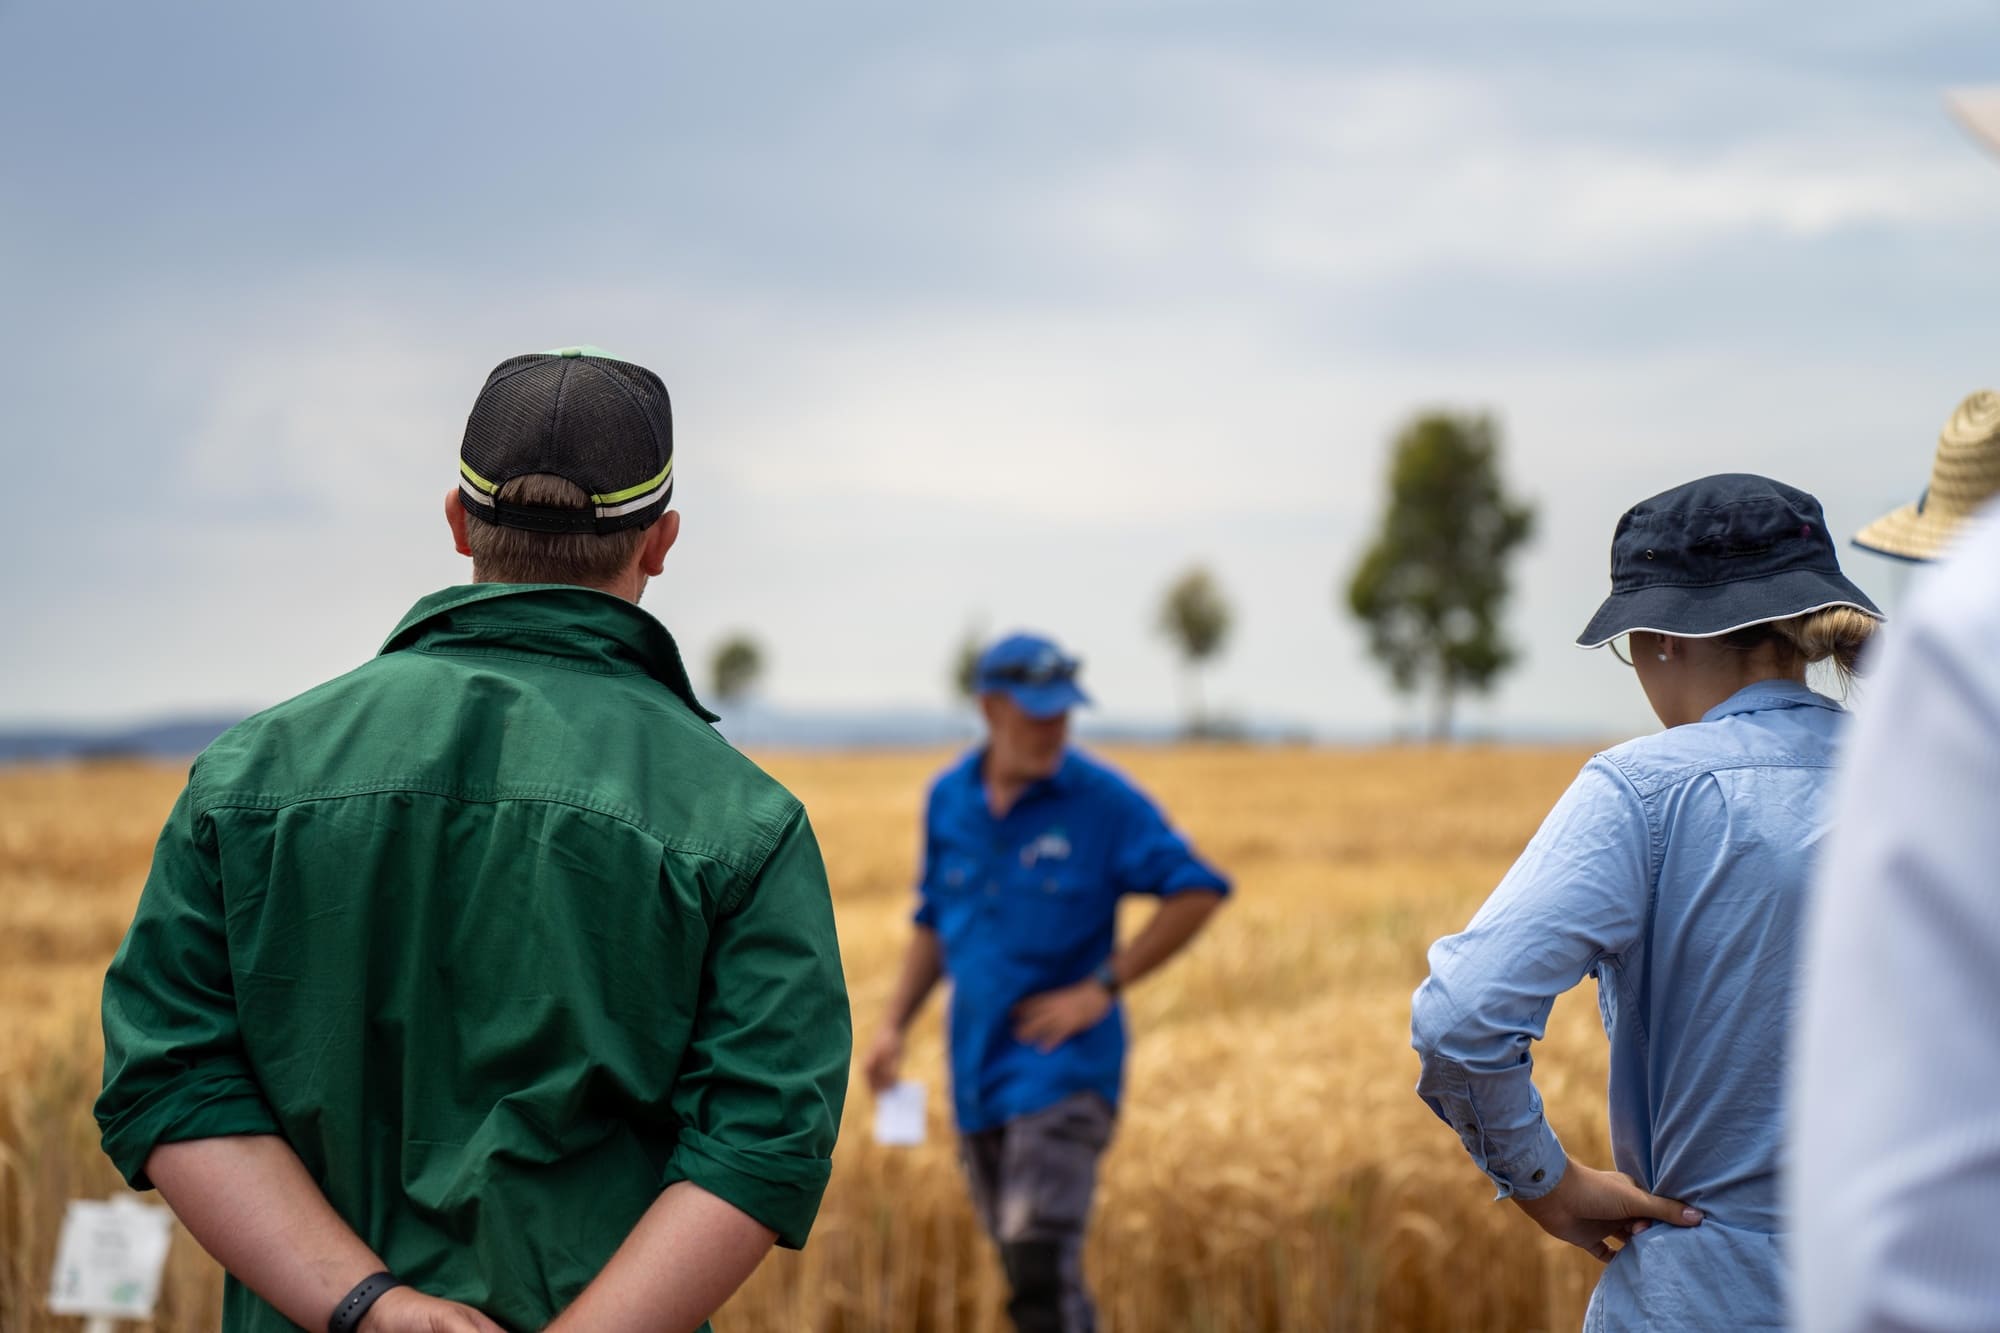
Succession planning involves family, business, wealth, tax and legacy considerations.
Ready to start the conversation?
Contact our experts below to discuss your family's succession planning journey.
Tim Mouritz
Partner, Accounting & Business Advisory
Clive Todd
Partner, Superannuation & Wealth Management